Understanding Tax on Asset Disposals
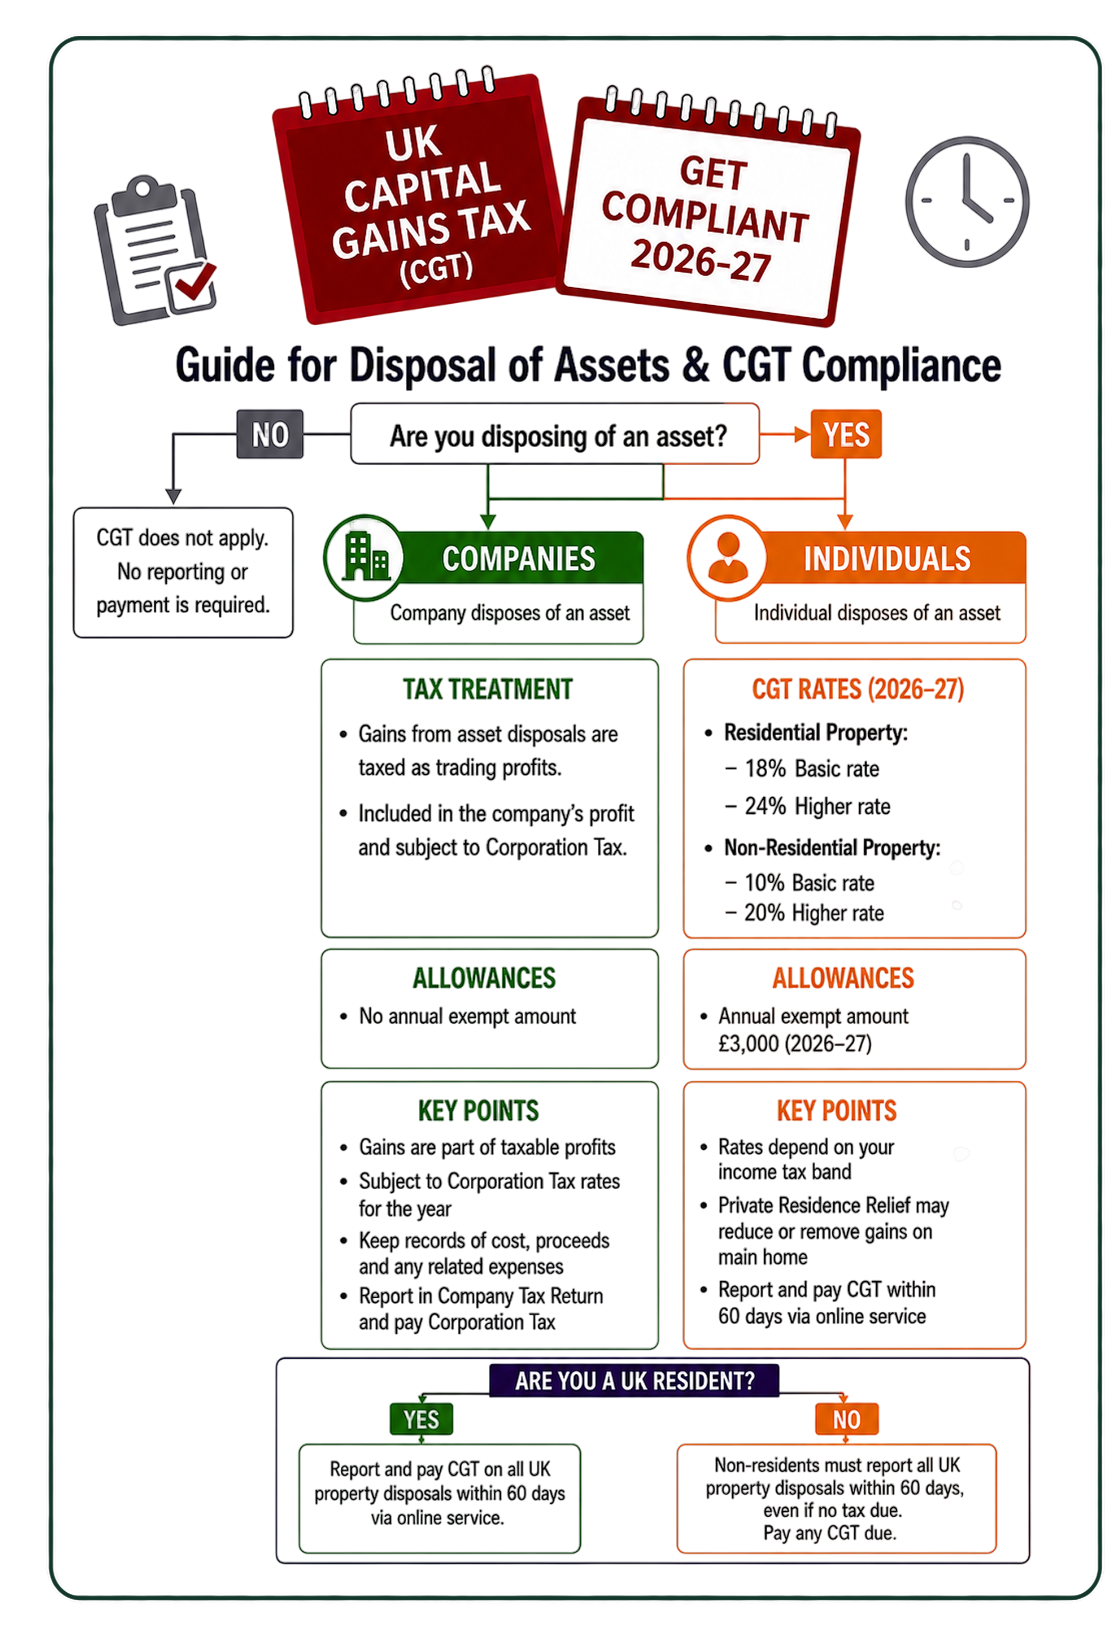
CGT is charged on the gain when you dispose of an asset that has increased in value. You pay tax on the gain, not the full sale price. Common examples include residential and buy-to-let property, shares, business assets and cryptoassets. The gain is usually calculated by deducting the original cost, along with allowable costs such as legal fees and improvement expenditure, from the disposal proceeds, so keeping accurate records from the day you acquire an asset is essential. Receipts, completion statements, valuations and contract notes can become important many years later.
A disposal isn’t always a sale. Gifting or exchanging an asset, or certain transfers such as a divorce settlement, can also trigger CGT. Losses can often be set against gains in the same year or carried forward. Companies don’t pay CGT: their gains fall under Corporation Tax instead. Residential property disposals have strict reporting deadlines, so act promptly after completion. Because the rules differ depending on the type of asset, who owns it and when it was acquired, it is worth getting advice before you commit to a sale, gift or transfer.
Our support helps you organise transaction records, review acquisition and disposal costs, identify relevant reliefs and prepare calculations, giving you a clearer understanding of potential liabilities and reporting responsibilities. We also review annual exemptions, losses brought forward and reliefs that may reduce the amount of tax payable. Clear guidance helps you understand the tax implications before making disposal decisions. Whether you are selling a rental property, shares or other assets, we explain each step in plain language, helping you budget for any tax due and respond confidently to later queries from HMRC. We keep your records consistent so each new disposal is easier to calculate and report.
Benefits of working with a CGT specialist
Time savings in peak season
We handle your calculation during the busy Self Assessment period and property transaction spikes.
Lower risk of costly errors
Specialist review reduces miscalculations that lead to enquiries, penalties or unexpected bills.
Faster turnaround
We help you meet the 60-day property reporting deadline.
Confidentiality and security
GDPR-compliant, secure processes at every stage.
Areas of CGT we cover
| Area | What We Handle |
|---|---|
| Residential property | 60-day returns, allowable costs and Private Residence Relief |
| Buy-to-let and additional properties | Improvement expenditure, letting history and changes of use |
| Shares and investments | Section 104 pooling and bed-and-breakfasting rules |
| Business asset disposals | Gain computations and Business Asset Disposal Relief |
| Cryptoassets | Disposals, staking and swaps across wallets and exchanges |
| Gifts of assets | Valuations and Gift Hold-Over Relief |
| Trusts and estates | Computations for trustees and personal representatives |
| Non-UK residents | Non-Resident CGT on UK property |
| Divorce and separation | Transfers between separating spouses and civil partners |
| Loss relief tracking | Carrying forward and offsetting losses correctly |
Our process
Initial consultation
We discuss your disposal and agree how we’ll work together.
Secure data submission
You upload your information through a secure, GDPR-compliant portal.
Computation and specialist review
We prepare the calculation and apply a second-review quality check.
Quality-checked output
You receive a clear, reviewed computation for your records or HMRC.
Filing preparation support
We help prepare SA108 pages or the 60-day property return.
Ongoing support
Your account manager stays available for questions and future disposals.
Frequently Asked Questions
Let’s Discuss Your Requirements
Have a question about our services? Speak with our team to discuss your engagement, deadlines and the support you need.
What Is the Deadline for Reporting CGT on UK Property?
UK residents who dispose of residential property with a CGT liability must report and pay within 60 days of completion. Because this deadline is separate from the standard Self Assessment timetable, we recommend speaking to us before you sell, so your records are ready and you know what to expect.
Do I Pay CGT If I don’t Sell an Asset?
Not usually. CGT is triggered by a disposal, such as a sale, gift, exchange or certain transfers. Simply owning an asset that has increased in value does not create a CGT charge, but it is still important to keep your purchase records, as you will need them when you eventually dispose of it.
Do you Handle CGT for Non-UK Residents?
Yes, including Non-Resident CGT on UK land and property. The rules depend on your residency and the type of asset, so we review your circumstances first and explain your reporting responsibilities clearly.
What Information do you Need?
Acquisition and disposal details and dates, costs, improvement expenditure, relief claims and ownership structure. We give you a simple checklist, and you can upload your information through our secure, GDPR-compliant portal. The more complete your records, the quicker and more accurate the computation.
Which Reliefs Might Reduce my Liability?
Private Residence Relief, Business Asset Disposal Relief, Gift Hold-Over Relief, Rollover Relief and Incorporation Relief may apply. We assess eligibility every time. We also review annual exemptions and losses brought forward, so you only pay what is properly due.
Can you Help with CGT on Shares and Cryptoassets?
Yes. For shares we handle Section 104 pooling and the bed-and-breakfasting rules. For cryptoassets we cover disposals, staking and swaps across wallets and exchanges. We prepare the calculations from your transaction records and keep them organised for future disposals.
Which Costs can I Deduct from my Gain?
Typically the original purchase cost, legal and professional fees, and money spent improving the asset (as opposed to routine repairs or maintenance). We review your records to identify the costs that are allowable. Keeping receipts, completion statements and valuations from the day you acquire the asset makes this much easier.
How Is CGT Calculated on Shares?
For most shares, we apply Section 104 pooling and the bed-and-breakfasting rules to work out the cost of shares sold, which can be complex if you have bought and sold the same shares over time. We prepare a clear, reviewed computation, so you understand how the final figure was reached.